Table of contents
When a manufacturing founder starts exploring a sale, the buyer universe usually breaks down into three broad categories, and each one comes with a genuinely different set of tradeoffs. Understanding the differences up front saves a lot of wasted conversations later.
What Strategic Buyers Look For

A strategic buyer is typically a company already operating in your industry, a competitor, a supplier, or a customer looking to integrate backward or forward. The advantage is real: they understand your market, often move faster through diligence because they need less education about what you do, and can sometimes pay a premium if your business fills a specific gap in their portfolio.
The tradeoff is what usually comes after closing. Strategic buyers look for synergies: redundant roles eliminated, back-office functions consolidated, sometimes facilities relocated or closed, and your company’s brand identity absorbed into theirs. Leadership continuity is often limited to a defined transition period, after which the founder is expected to exit entirely.
How Private Equity Funds Structure a Deal

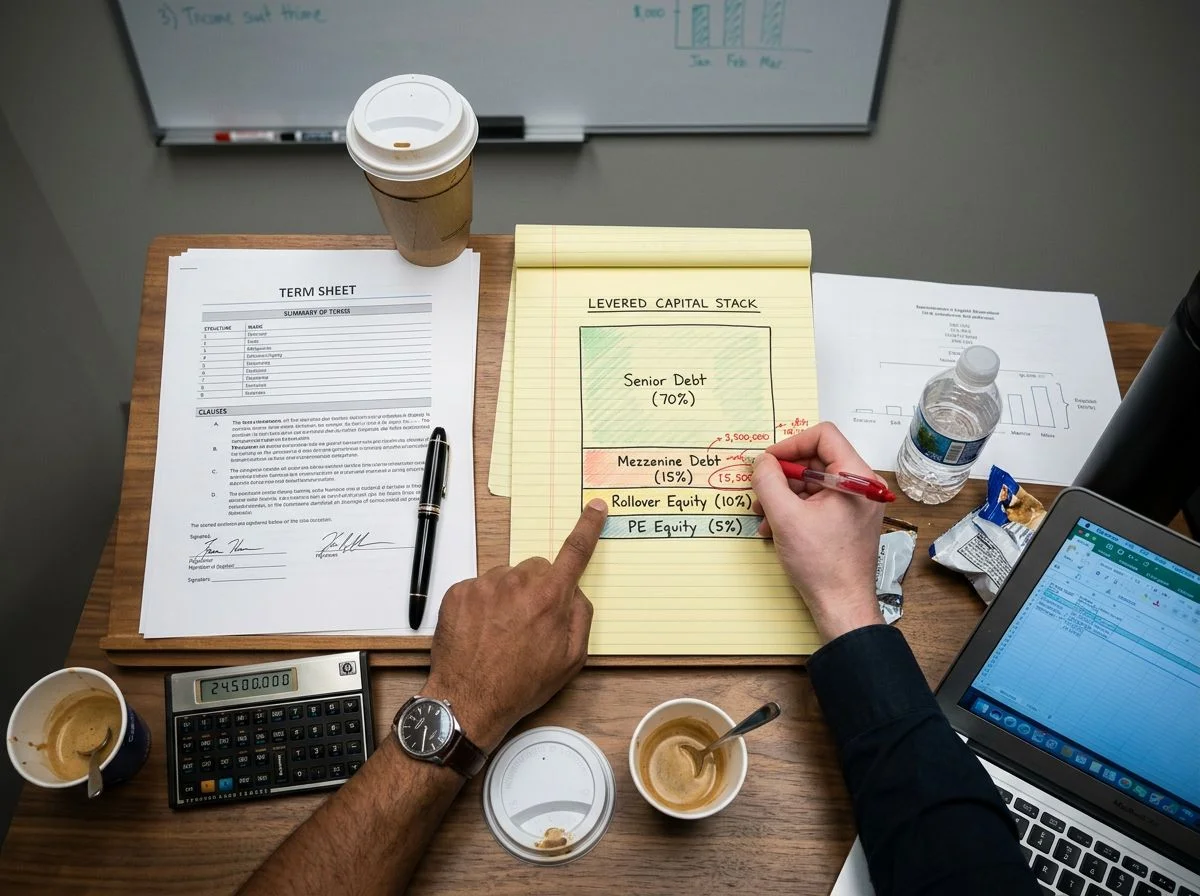
A private equity buyer brings capital and, in many cases, real operational expertise to help a business grow faster than it might otherwise. What it also brings is a fund structure: outside investors expecting a return within a defined window, typically 3 to 7 years, financed in part through debt secured against the acquired company.
That financing mix is well documented. GF Data, which tracks lower-middle-market private equity transactions, reported average debt on platform acquisitions at 2.9x trailing EBITDA in Q2 2026, down from 3.4x the prior quarter. That debt doesn’t belong to the fund. It belongs to the company being acquired.
That structure shapes almost everything that follows. Decisions get filtered through the eventual resale, capital allocation gets weighed against debt service, and the business will be sold again within 3-7 years. This means the business will face the same uncertainty again and again, instead of finding a permanent steward for the long term.
That window isn’t a worst-case estimate, either. Bain & Company’s 2026 Global Private Equity Report found that holding periods at exit now hover around seven years, up from an average of five to six years between 2010 and 2021. The clock is real, and lately it’s been getting longer, not shorter.
Why Founders Choose Strategic Permanent Capital

The third category is less familiar to a lot of owners, simply because it’s less common: a buyer structured specifically to hold acquired companies indefinitely, funded internally rather than through an external fund with its own return requirements. No planned exit, no fund clock, and, in models that avoid heavy leverage, no debt load imposed on the acquired business to finance its own purchase.
The tradeoff here is usually price ceiling, not speed. A permanent-capital buyer isn’t going to compete in an auction process or stretch to the top of a bidding range the way a strategic buyer chasing a specific synergy might. But we’re often faster to a decision than a PE fund or strategic buyer that needs sign-off from an investment committee or board of directors, since we’re not competing in bidding wars or relying on debt to get a deal done. What permanent capital offers instead is durability: the company’s future isn’t tied to a resale clock, and the leadership team and culture that built the business have a real chance of staying intact for decades, not years.
What Are You Actually Optimizing For?

If maximum headline price is the only variable that matters, a competitive process involving strategic buyers and PE funds will usually produce it. If what you’re optimizing for is your company’s independence, your team’s stability, and your legacy staying intact after you’re no longer running things day to day, permanent capital is worth understanding as a real option.
Wallbank Industrial operates as a permanent-capital buyer by design: internally funded, no outside investors, no planned exit. You can read a more detailed comparison of our model against the private equity approach here.
Still Have Questions?
We’re happy to answer any questions about our approach, acquisition criteria, or how we might be the right home for your business.
Get in Touch